Conventional wisdom dictates that retiring with debt — especially a debt as large and significant as a mortgage — is financially dicey at best and potentially ruinous at worst.
That’s not how Brian Lindmeier sees it. “It just doesn’t make any sense at all to pay off the house,” he said.
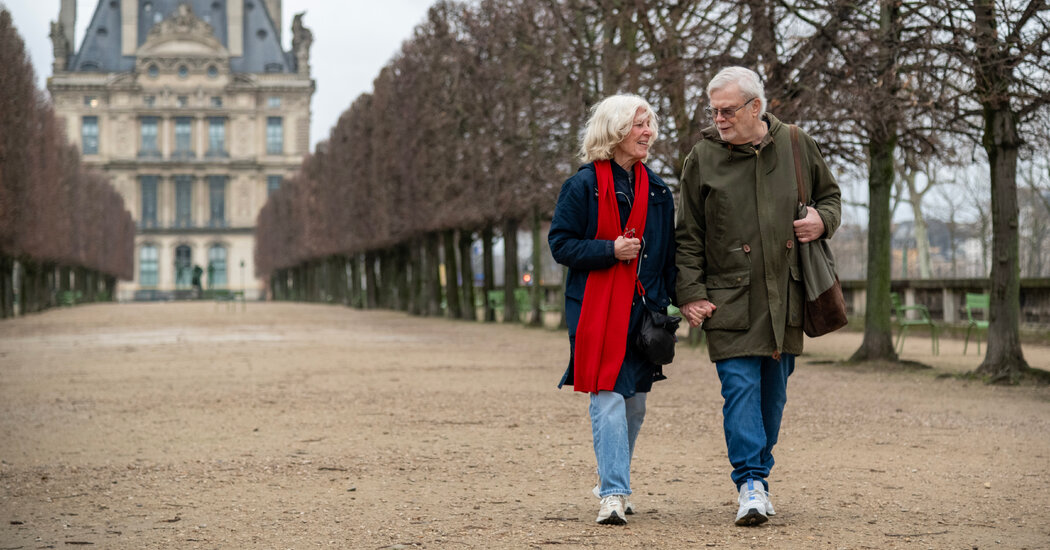
Mr. Lindmeier, 80, a retired purchasing and inventory manager, and his wife, Cindy, who retired from the local public school system, refinanced their home in Orange, Calif., at the end of 2020. They rolled over their balance into a new 30-year loan and slashed their interest rate in half to a rate below 3 percent. Mr. Lindmeier called the move a “no brainer.”
“The money I’d have to take out of my savings or out of my investments is yielding higher interest than the interest I’m paying on the loan,” he said.
For a growing number of older Americans, signing up for a mortgage that is likely to outlive them makes good economic sense. A significant percentage of homeowners have fixed-rate mortgages with historically low rates. Roughly six of 10 mortgage borrowers in the third quarter of last year held loans with interest rates of less than 4 percent, according to the online real estate brokerage Redfin. Nearly a quarter had rates of less than 3 percent.
A campaign of rate increases by the Federal Reserve, which is intended to tamp down inflation, has driven yields that investors can get on ultrasafe instruments like certificates of deposit to 5 percent or higher.
Even those who have spent years saving with the intention of paying off their mortgages with a lump sum at retirement are now finding themselves recalculating. Some are determining that those funds would be better deployed by earning returns on other investments or helping them meet their cash flow needs for everyday expenses.
Eric Zittel, chief lending officer at Financial Partners Credit Union in Downey, Calif., said a number of his members, including Mr. Lindmeier, are keeping their mortgages — and their cash.
“They’re realizing they can get a 4.5 percent to 5 percent rate just for a C.D. When you do the math, it makes a lot more sense for them to keep those funds.”
A number of financial advisers and retirement planners argue that the imperative to pay off a mortgage before retirement is an outdated axiom in the current economic climate.
“While paying off a debt feels like a very conservative, secure move, trading your liquidity for a paid-off mortgage is quite risky,” said Evan Beach, president of Exit 59 Advisory, a wealth management firm focusing on retirement-income planning in Alexandria, Va. “You’re giving up money in your pocket that you may actually need for something else.”
Gary Jacobs, a client of Mr. Beach’s and a retired federal employee, and his wife, Donna, a retired nurse, refinanced the mortgage on their home in Chevy Chase, Md., at the end of 2021 when mortgage rates were at a historic trough.
“Timing is everything, and we timed it just right this time,” Mr. Jacobs, 79, said. Refinancing into a new 30-year mortgage at a rate roughly half of their previous interest rate lowered the couple’s monthly payment by around $300.
“Although we could have, we didn’t feel like drawing down on our cash reserves in order to pay the mortgage off,” Mr. Jacobs said, adding that paying off the mortgage would have taken about half of their savings. “We’re conservative in the sense of wanting to be prepared for eventualities where we might need the cash.”

This dynamic is one factor driving historically large percentages of older Americans to carry mortgage debt into their senior years, according to a new report from the Joint Center for Housing Studies of Harvard University. In 2022, researchers found that just over 40 percent of homeowners older than 64 had a mortgage, a jump from roughly 25 percent a generation ago.
Ultralow mortgage rates were a big driver of the increase, said Jennifer Molinsky, project director of the center’s housing and aging society program. “We do think that, for some people, there is a calculated financial decision that they’d prefer to keep their mortgage, even if they could pay it off, and invest it elsewhere,” she said.
But Ms. Molinsky expressed concern that the increase came in tandem with an overall rising debt load among seniors. “There’s a trend among all older adults that there’s a higher level of debt across the board,” she said.
The downside of having a mortgage
Retirees on fixed incomes may struggle to manage higher-interest and variable-rate debt like outstanding credit card balances. In a worst-case scenario, if a health crisis or the death of a spouse destabilizes their life or their finances, older Americans could be at risk of losing their homes.
“For a lower-income senior, homeownership can sometimes become challenging, because when people enter their retirement years, they often see a decrease in income,” said Lori Trawinski, director of finance and employment for the AARP Public Policy Institute.
While the recent run-up in home prices has given homeowners more equity on paper, this can pose a challenge for those on fixed incomes since those higher valuations can lead to higher property taxes and insurance premiums.
Some experts in elder finance and policy point out that because a mortgage is almost always the biggest component of a homeowner’s monthly expenses, homeowners in their 50s and 60s have less resilience to absorb a financial hit like as unexpected job loss or caregiving demands.
“Housing is the biggest chunk of that budget for everybody, so it’s undoubtedly more expensive on a month-to-month basis to have a mortgage than to have a home that’s paid off,” said Beth Truesdale, a research fellow at the W.E. Upjohn Institute for Employment Research.
While people might intend to remain employed until they are able to draw Social Security, Ms. Truesdale said, her research indicates that only about half of American workers remain employed throughout their 50s. This suggests that an income-reducing event is more common than many people expect. While the drop in labor force participation is more pronounced among women and less-educated workers, the employment rate drops by about 20 percentage points among all demographics for people in their 50s.
“Even for people who start out with the advantages, there’s no guarantee they can work as long as they want to,” Ms. Truesdale said.
For those who own their homes free and clear, the Joint Center for Housing Studies found that older Americans often struggle to tap the equity locked up in their homes. And those homes might not be as valuable as their owners believe. Ms. Trawinski of the AARP said longtime homeowners might be content living with, for instance, outdated kitchens or bathrooms.
“It often happens that people will not do those kinds of upgrades,” she said. Older homeowners might also have mobility limitations or other physical challenges that make maintenance and upkeep of a property more challenging.
Lower-income senior homeowners, who are more likely to be people of color, are also more liable to struggle to pay for necessary repairs and upgrades. “There’s less ability to invest in that property and maintain it over time,” Ms. Molinsky of the center for housing studies said. “People need to maintain the value of that asset if they want to use that equity later in life,” but, she added, maintenance can entail significant costs.
The effect that housing costs can have on the average household budget can prompt some people to view a mortgage as a risky obligation to carry into retirement — in some cases, whether that concern is warranted or not, said David Frisch, founder of Frisch Financial Group in Melville, N.Y.
“In addition to the financial calculations, it’s also psychological in terms of risk,” he said, adding that even when the math suggests that maintaining a mortgage would cost less than paying it off, some homeowners’ intense aversion to debt influences their choices. “Some people don’t want that mortgage payment hanging over their head even though they’re earning more” by keeping that cash in C.D.s or Treasury securities, he said.
Some financial planners embrace a less-debt-is-better philosophy, as well. Jamie Cox, managing partner of Harris Financial Group in Richmond, Va., said a homeowner’s psychological approach to debt plays a role in his reluctance to encourage a client to hold onto a mortgage.
During the financial crisis, Mr. Cox said, his clients with paid-off mortgages were more sanguine about the drop in their portfolios because they didn’t have that obligation hanging over their heads. “They’re better investors because they’re not afraid of losing their homes,” he said.
Figuring out what’s best for you
No single decision will work for everyone, so financial planners suggest that homeowners at or near retirement consider the specifics of their mortgage terms, cost of living and risk tolerance, along with the following points:
If you took advantage of historically low rates to refinance, it’s possible that you could earn a higher yield by keeping money earmarked for a mortgage payoff in safe investments like C.D.s or Treasuries.
Financial advisers warn against paying off a mortgage if doing so would leave you with little or no emergency savings. Advisers typically suggest keeping an emergency fund of between three and six months’ worth of living expenses in cash or similarly liquid instruments.
Your personal risk tolerance matters. Saving a couple hundred dollars a month shouldn’t come at the price of your peace of mind.