Close Menu

    Subscribe to Updates

    Get the latest creative news from FooBar about art, design and business.

    What's Hot

    Talk Your Book: The Case for Value and Momentum

    October 20, 2026

    Trump Feels ‘Very Sad’ And Unappreciated, Judge And DOJ Spar Over Golf Course Case: Latest Updates

    October 20, 2026

    I Tried Strava’s New Strength Coach Feature, and I’m Optimistic

    October 20, 2026
    Facebook X (Twitter) Instagram
    Trending
    • Talk Your Book: The Case for Value and Momentum
    • Trump Feels ‘Very Sad’ And Unappreciated, Judge And DOJ Spar Over Golf Course Case: Latest Updates
    • I Tried Strava’s New Strength Coach Feature, and I’m Optimistic
    • 6 Questions to Ask Before Hiring a Speaker For Your Next Event
    • Vaden Consultancy – Company Profile
    • Donald Trump Is Learning That He Can’t Steal This Election
    • 13 Shocking Historical Sex Laws I Can’t Believe Were Real
    • What it is and how it works
    Facebook X (Twitter)
    SBM Global News
    Demo
    • Home
    • Top Stories
      • Politics
    • Business
      • Small Business
      • Marketing
    • Finance
      • Investment
    • Technology

      Vaden Consultancy – Company Profile

      October 20, 2026
      Read More

      No agenda, no rush, no leaving San Francisco: Benchmark’s partners on investing in a frenzied market

      October 19, 2026
      Read More

      CredentialCamp – Company Profile – AllBusiness.com

      October 18, 2026
      Read More

      Ember’s new temperature-controlled mug makes my nightly tea ritual even better

      October 18, 2026
      Read More

      Clevra – Company Profile – AllBusiness.com

      October 17, 2026
      Read More
    • Lifestyle
      • Travel
    • Feel Good
    • Get In Touch
    SBM Global News
    Demo
    Home»Investment»$150,000 or $1.5 Million or $5 Million
    Investment

    $150,000 or $1.5 Million or $5 Million

    By Staff WriterJune 26, 20266 Mins Read
    Facebook Twitter LinkedIn Reddit Email
    #image_title
    Share
    Facebook Twitter LinkedIn Pinterest Email

    There were a lot of good questions that came in this week so let’s knock out a handful of the best ones.

    A reader asks:

    I listened to your interview on “The Bull” and wanted to ask – if you had $150k in cash today, how would you enter the stock market? I was thinking of building a portfolio with a global equity fund like the FTSE all world along side a 1-3yr government bond ETF and a gold ETF but I’m stuck on how to go about entering the market.

    What to do with a lump sum of cash is one of the most popular questions I’ve received over the years.

    It’s been a question for years and will always be a question going forward because it can be scary putting a big slug of money to work in risk assets.

    The math says you should just invest the money and move on with your life because most of the time the stock market goes up.

    But sometimes it goes down.

    The worry is you are personally going to anger the market gods and thus see a portion of your lump sum evaporate right after investing it.

    This is why so many investors are more comfortable dollar cost averaging or putting half in now and the other half periodically.

    Regret minimization is a useful strategy even if it’s not always the most optimal route.

    But this question isn’t just about the stock market. He’s talking about a diversified portfolio of stocks, gold and cash.

    The beauty of a diversified portfolio with a pre-established asset allocation is you don’t really need to worry about the timing quite so much.

    If you invest in some combination of stocks, gold and fixed income or other asset classes you have the ability to redeploy if prices fall by simply rebalancing.

    Demo

    Guess how many times stocks, gold and short duration bonds have declined in the same year?

    Zero times!

    Gold and stocks have only simultaneously finished down in the same year four times in the past 75 years or so.1

    Diversification takes away the need to predict the future in many ways.

    Pick an asset allocation. Deploy your money. Rebalance when necessary.

    Another reader asks:

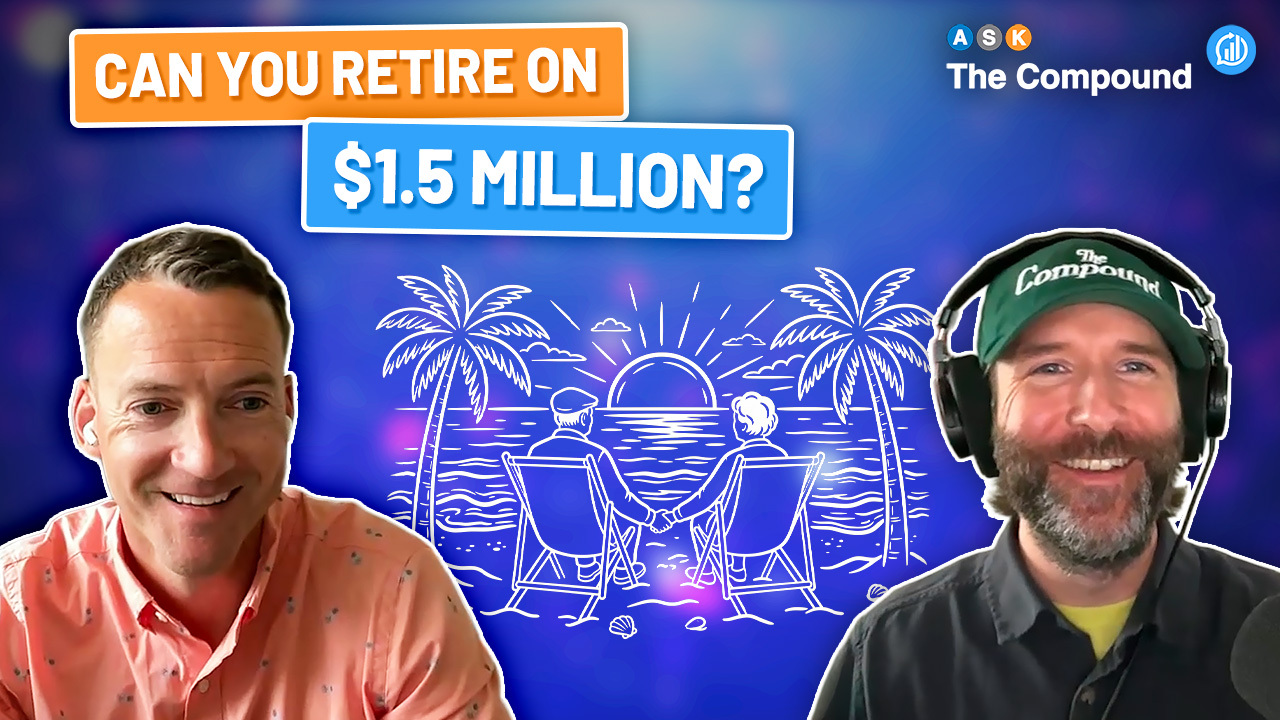
    My parents are considering retirement in a couple of years. Dad will be collecting his Social Security next year which will cover most of their living expenses. However, they’ve been debating how much they need in order to feel safe retiring. Their goal is $1.5 million, but my mom is nervous about it not being enough (what if they outlive the money). They have everything paid off and I would guess their cost of living is about $30,000 per year. They’re very frugal and always have been. What would you tell them?

    If you retire at age 65 with $1.5 million in liquid assets (no home equity) that puts you in the top 15% or so of people your age. Your parents are rich!

    The average Social Security check is a little more than $2,000 a month. If both spouses receive an average check size that’s almost $50,000 a year.

    Based on a $30,000 annual run rate your parents are more than prepared for retirement. Social Security alone will more or less cover them.

    Your mom is worried about outliving their money. Social Security is the perfect longevity insurance.

    It’s a government-backed annuity that automatically adjusts for inflation and pays you out until death.

    Your parents could invest in a balanced portfolio, pull $50k to $60k or so a year and enjoy their retirement with relative ease.

    Once you have the math part of the equation figured out financial planning becomes more about defining the kind of life you want to purchase with your finances.

    Your parents need a plan for their money but also a plan for their time and enjoyment.

    Still another reader asks:

    How often do you see people with $5M+ invested solely in things like VTI, SPY or the usual low-cost index funds through retirement? Isn’t this how people like Warren Buffett take a disciplined approach to market psychology? If one lives their life with reasonable expenses in retirement, so what if a market drop destroys 30%? Isn’t the potential upside of more growth worth it?

    One of the most important topics I studied for the level 3 CFA exam covered how to define your risk profile.

    Your risk profile boils down to a combination of your willingness, need and ability to take risk:

    Need: The return required to reach your financial goals.

    Ability: Your financial circumstances — time horizon, income, portfolio size, liquidity needs, spending habits, savings rate, etc.

    Willingness: The balance between your desire to grow your portfolio and your desire to sleep soundly at night.

    Many wealth managers assume once you’ve won the game you should stop playing. Why take more risk when you don’t need to.

    But with a large portfolio you also have the ability to take more risk. What’s the harm?

    This is why your willingness to take risk becomes the emotional fulcrum of your investment plan when you have the ability but not the need to take more risk.

    Providing investment advice to ultra high net worth clients can be surprisingly difficult because there are fewer limitations.

    It almost doesn’t matter what you invest in with a $10 million portfolio. Uber aggressive? Sure. Super conservative? That would work too.

    A successful investment process requires some limitations.

    I have seen ultra high net worth clients invest most or all of their money in stocks.

    I’ve also seen people with 8-figure portfolios that aren’t so high octane.

    It really depends on your tolerance for risk, time horizon and goals.

    Do you want to sleep better at night? Give away all of your money to charity? Grow the portfolio for the next generation?

    Whether you have $150k, $1.5 million or $5+ million, the question of how much risk to take is a personal one.

    There are quantitative metrics to use but the qualitative piece will always matter more.

    Know thyself is a good starting point.

    I hit on all of these questions and more on this week’s all new episode of Ask the Compound:


    Further Reading:
    Half a Million Dollars

    1The average decline for the S&P 500 in those years was a loss of just 5%.

    View original article here

    Share. Facebook Twitter LinkedIn Email Reddit
    Previous ArticleTrump Has All-Caps Freakout About 1 Of His Most Sensitive Topics
    Next Article Trump-Backed Candidate Sparks Outrage With Holocaust Remark About Jewish Democrat

    Related Posts

    Talk Your Book: The Case for Value and Momentum

    October 20, 2026
    Read More

    What’s the Right Level of Interest Rates For the Economy?

    October 18, 2026
    Read More

    Hedging the AI Trade – A Wealth of Common Sense

    October 16, 2026
    Read More
    Add A Comment

    Leave A Reply Cancel Reply

    Demo
    Top Posts

    Former FBI, CIA Head Has ‘Serious Concerns’ With Trump Cabinet Picks

    December 28, 2024435

    Emirates to operate next-gen A350 on the third daily service to Cape Town

    January 14, 2026256

    AAVE Price Prediction: Target $215-225 by Mid-January 2025 as Technical Indicators Signal Bullish Momentum

    December 15, 2025240

    Wall Street Slumps As Alphabet, Qualcomm And Other Tech Stocks Fall

    February 7, 2026212
    Don't Miss
    Investment

    Talk Your Book: The Case for Value and Momentum

    By Staff WriterOctober 20, 20263 Mins Read

    Posted October 19, 2026 by Ben Carlson Today’s Talk Your Book is brought to you…

    Read More

    Trump Feels ‘Very Sad’ And Unappreciated, Judge And DOJ Spar Over Golf Course Case: Latest Updates

    October 20, 2026

    I Tried Strava’s New Strength Coach Feature, and I’m Optimistic

    October 20, 2026

    6 Questions to Ask Before Hiring a Speaker For Your Next Event

    October 20, 2026
    Stay In Touch
    • Facebook
    • Twitter
    Demo
    Find More
    Trending News
    • Talk Your Book: The Case for Value and Momentum
    • Trump Feels ‘Very Sad’ And Unappreciated, Judge And DOJ Spar Over Golf Course Case: Latest Updates
    • I Tried Strava’s New Strength Coach Feature, and I’m Optimistic
    • 6 Questions to Ask Before Hiring a Speaker For Your Next Event
    • Vaden Consultancy – Company Profile
    • Donald Trump Is Learning That He Can’t Steal This Election
    • 13 Shocking Historical Sex Laws I Can’t Believe Were Real
    • What it is and how it works
    • No agenda, no rush, no leaving San Francisco: Benchmark’s partners on investing in a frenzied market
    • Will Disneyland Move the Matterhorn for Tomorrowland’s Reimagining? Why We’re Skeptical of Rumors
    Other News
    • Business
    • Feel Good
    • Finance
    • Fitness
    • Health
    • Investment
    • Lifestyle
    • Marketing
    • Politics
    • Small Business
    • Technology
    • Top Stories
    • Travel
    About Us

    Small Business Minder brings together business and related news from around the world in one place. Follow us for all the business news you'll need.

    Facebook X (Twitter)
    Our Picks

    Talk Your Book: The Case for Value and Momentum

    October 20, 2026

    Trump Feels ‘Very Sad’ And Unappreciated, Judge And DOJ Spar Over Golf Course Case: Latest Updates

    October 20, 2026
    Most Popular

    Former FBI, CIA Head Has ‘Serious Concerns’ With Trump Cabinet Picks

    December 28, 2024435

    Emirates to operate next-gen A350 on the third daily service to Cape Town

    January 14, 2026256
    Categories
    © 2026 Small Business Minder
    • Home
    • Get In Touch

    Type above and press Enter to search. Press Esc to cancel.

    Ad Blocker Enabled!
    Ad Blocker Enabled!
    Our website is made possible by displaying online advertisements to our visitors. To get the most from our site, please disable your Ad Blocker.