The 2017 tax cuts are expiring. Reformers are lying in wait. Your investment strategy now should reflect the odds of law changes later.
By William Baldwin, Senior Contributor
Loss harvesting—the selective sale of underwater positions in order to capture capital losses—is quite the nice trick. Could it be outlawed? What about all the other tax-minimizing schemes that investors use? The bitcoin wash, the grantor trust swap, the gift of appreciated property, the Roth conversion, the qualified charitable donation, the freebie for the dead—the parade is long, and none of these goodies is guaranteed to last forever.
What Congress has granted, Congress can take away. What follows here is a survey of tax strategies that you are or should be using, hints at the odds they will be deleted and recipes for what to do now.
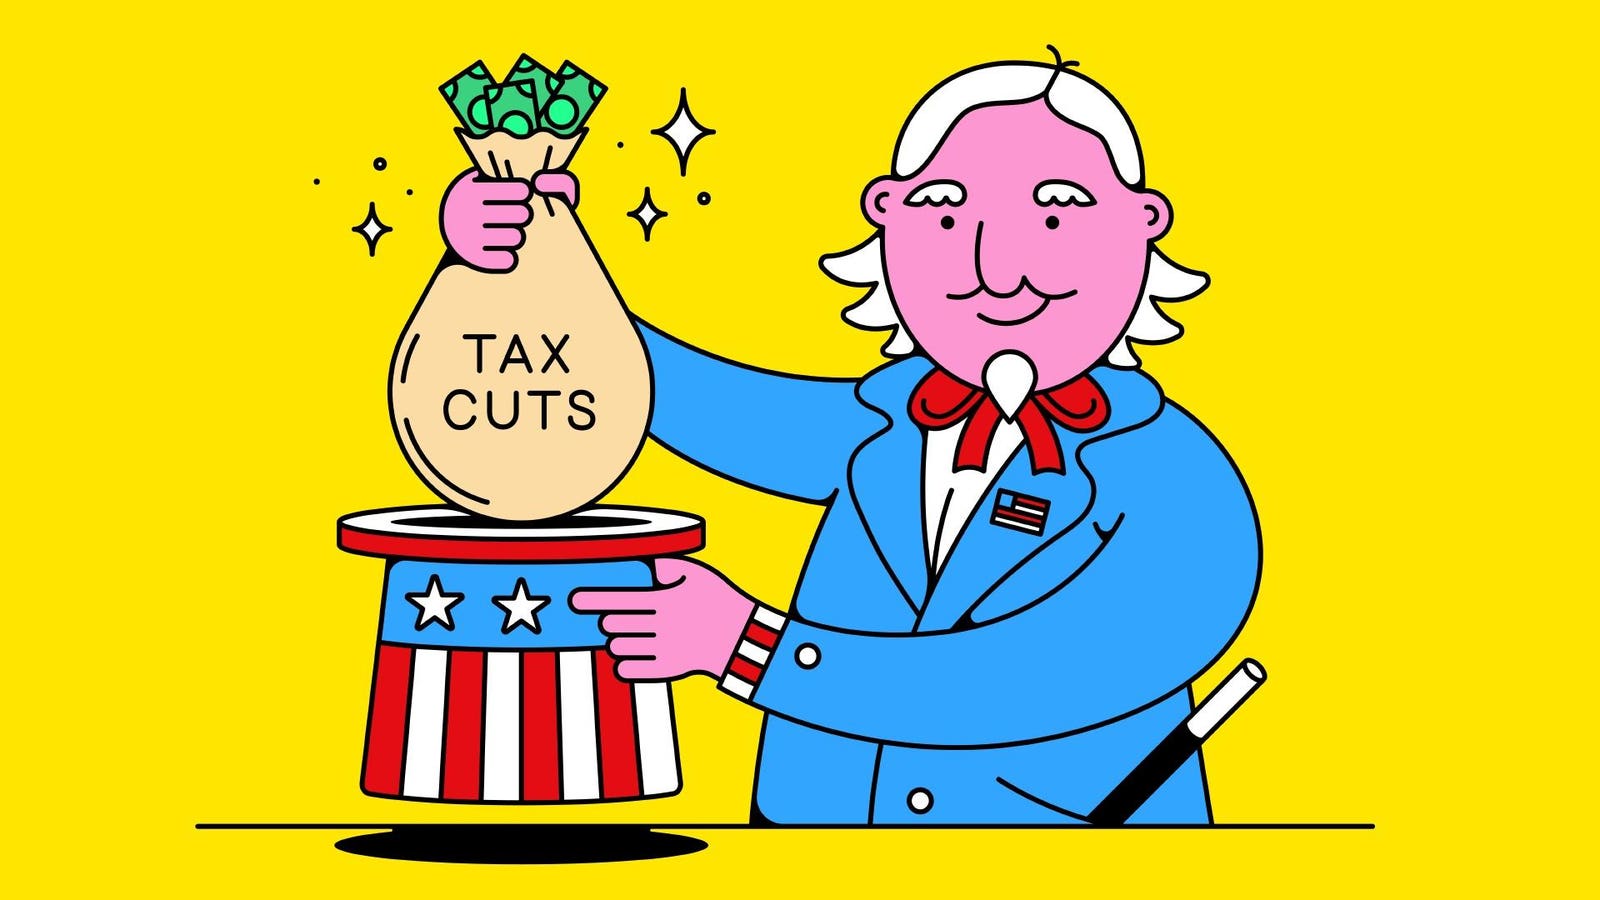
The risk of tax increases on savers comes in two forms. One is the December 31, 2025 sunsetting of the 2017 tax cuts. An extension is possible but would demand cooperation between legislators and the president along with a certain obliviousness to the federal budget deficit. Without an extension, high-income taxpayers will see their marginal rates go from 37% to 39.6% and many middle-class taxpayers will suffer a boost from 24% to either 28% or 33%.
The other hazard is the possibility that both Congress and the White House will be in the hands of politicians looking to close “loopholes,” a loophole being defined as any mechanism that allows you to keep money you have earned. The Biden administration’s recent budget book has a hit list of proposals for cracking down on prosperous taxpayers. The probability of enactment this year is nil. After the election, anything is possible.
Loss harvesting enables you to report a capital loss at a time when your portfolio is in fact coining money. It is based on a century-old feature of the income tax that subjects appreciation to tax only when the owner chooses to sell the asset. So, you unload the six clunkers in your portfolio while letting the 60 winners ride. The exceptions to this realization rule are narrow, principally involving commodity and stock index futures.
PROJECTED TAX BRACKETS FOR 2026
Estimated brackets after sunset of 2017 tax cuts if inflation continues; married joint returns
Parametric Portfolio Associates, a unit of Morgan Stanley that oversees $475 billion, has made loss harvesting into an art form. Since 1992 it has run synthetic index funds, consisting of several hundred stocks booked as individual positions in each client’s portfolio. That allows it to periodically sell off just the losers, replacing missing pieces after a 31-day waiting period. The resulting capital losses can absorb $3,000 a year of ordinary income plus any amount of gains that are cropping up elsewhere in the client’s tax return (such as from participation in a hedge fund or the sale of a vacation home).
Is Parametric threatened by tax reform? Somewhat. A proposal on the table in 2017 (but omitted from the legislation) would have forced investors to use first-in-first-out accounting for stock positions assembled over a long period, rather than do what Parametric’s computers now undertake on their behalf, which is to sell the lot that minimizes the tax bill. The firm was ready with some software changes that would have minimized the damage from FIFO, says Jeremy Milleson, director of investment strategy.
What about the distinct possibility that rates will be higher in two years? Milleson has an answer for that, too: “The value of harvesting losses increases as tax rates go up.”
Our catalog of tax dodges begins with one that is at the heart of what makes loss harvesting valuable to the wealthy.
STEP-UP
The tax code exempts gains unrealized at the owner’s death. Thus, if you bought $10,000 of Nvidia, it’s now worth $100,000 and tomorrow you get run over by a cab, neither you nor your heirs owe tax on the $90,000 gain. This is important to Parametric; the ideal client dies with a lot of unrealized gains.
Eliminating the step-up has been a yearning of reformers at least since 1970. The Biden hit list takes a lurch in that direction by limiting the exclusion to $5 million of gain.
What to do: If your portfolio is diversified, nothing. If it’s overweight one big winner, such as an employer’s stock, the risk of a law change might make you slightly more inclined to lighten the position.

ROTH CONVERSION
It often makes sense to prepay income tax on some retirement assets in a pretax account. The game is to convert enough each year to fill up a tax bracket but not go over.
At risk in a reform law? No. The conversion delivers cash to the Treasury at the expense of a greater tax collection down the road. You can count on politicians to be short-sighted.
What to do: Work with an accountant. This gets complicated.
LOW RATES
There’s a considerable risk that taxes will go up on incomes over $400,000.
What to do: Think about accelerating some income. It might make sense to do some Roth converting now, when rates are low. Another kind of ordinary income can come from so-called passive investments. Some of these (master limited partnerships, for example) create boomerang income on your departure. If you were going to sell anyway, maybe do that now rather than later.
Other side of the coin: You have a sickly passive investment (rent-controlled apartments? Broadway show?) whose losses remain suspended until you complete your exit. Might make sense to plan the exit for 2026.
MORTGAGE INTEREST
The 2017 tax cut, by limiting the itemized deduction for state and local taxes and by greatly expanding the standard deduction, made the deduction for interest pointless for many taxpayers. If the politicians elected this November can’t agree on what to do about extending the 2017 law, the mortgage deduction will come back to life.
What to do: Hesitate before paying off your mortgage. Suppose you have a 6% mortgage and also a Roth (i.e., aftertax) account earning 5% on a comparable risk-free asset, like a 20-year Treasury bond. With today’s tax code, you’d come out ahead paying down the mortgage. But two years from now, if tax rates pop up and you’re again deducting interest, the aftertax cost of that mortgage will drop to 4%. You’ll wish you still had the bond.
GIFTS TO RELATIVES
At present, the tax law calls for a carryover of basis when an asset is transferred. You bought stock a long while ago for $2,000, it’s now worth $18,000 and you give it to your niece, who sells. The $16,000 of gain goes on her tax return. If her salary is low, the gain will be taxed at a low or even 0% rate.
The Biden hit list calls for treating such a gift as a sale, taxable on your return. As with the step-up, there would be a $5 million cumulative lifetime exemption. If a future Congress is hungry for revenue, $5 million will seem too generous. A $50,000 lifetime exemption might look right.
What to do: Enjoy this gimmick while you can.
A cousin to this strategy has you donating assets containing long-term gains to charity; your itemized deduction is equal to the current market value but the appreciation is never taxed. If charity is your end game then you probably have nothing to fear from a tax reform.
THE BITCOIN WASH
The law limiting capital losses on wash sales (sales followed or preceded by purchase of the same things within 30 days) does not apply to digital assets. Reformers are aching to correct this omission.
What to do: It doesn’t matter what odds you place on a law change; it almost always makes sense to harvest a loss as soon as you can. If you buy virtual currency at $64,000 and it sinks to $50,000, sell it and buy it back a day later.
THE 20% PASS-THROUGH
A peculiar feature of the 2017 tax law, possibly a reflection of the fact that a prominent Republican is in real estate, exempts from tax 20% of income earned from unincorporated businesses. It helps plumbers, website designers and other self-employed people if their income is not too high. It helps real estate owners no matter what their income. It makes dividends from real estate investment trusts partly exempt. The pass-through deduction is hard to defend, so an extension beyond next year’s sunset is somewhat unlikely.
What to do: Put any new REIT positions in a tax-protected account.
THE $13.6 MILLION EXCLUSION
The sunset cuts this estate/gift tax exclusion in half. It’s a toss-up whether enemies of the estate tax will have the votes to get the more generous exclusion extended. Even if the exclusion reverts to a lower amount, though, it’s likely that gifts made under the aegis of the high amount will not be retroactively taxed.
What to do: If you have this kind of money, think about giving heirs a chunk of it now. But before deeding a castle to your daughter, reread King Lear.
TRUST TRICKS
One popular scheme has you getting appreciating assets out of your taxable estate by handing them over to an irrevocable trust while retaining just enough control that income from the assets gets taxed on your return because it’s a “grantor trust.” (Goofy. Don’t trust to make sense of it.) So you get the income tax outlay out of your estate as well.
An enhancement has you swapping your cash for a trust asset after the asset has appreciated. That puts the asset back in your estate, where it benefits from the step-up (see above). Yet another estate planning maneuver involves taking back a lifetime annuity from a trust so that the residual value going to heirs is ostensibly low.
Biden proposes to end all these shenanigans. Someday the reformers will win this battle.
What to do: Talk to your lawyer now.
THE CHARITABLE RETIREMENT
Once you turn 70-1/2, you can send up to $100,000 a year from an IRA directly to a charity, keeping the distribution out of your adjusted gross income. This incentive for generosity, which goes by the name qualified charitable donation, does not appear to be on anybody’s hit list.
What to do: Wait until the year you turn 73 to turn on the QCD spigot. That way it will have the added advantage of lowering your required taxable distributions.
Related technique: If you plan to leave some money to your kids and some to charity, make the kids the primary beneficiaries of your taxable IRA and a charity the contingent one. Your executor can arrange to have the heirs disclaim the IRA to the extent appropriate while taking assets that don’t have an income tax burden.
The potential use of an IRA for charity is one reason not to overdo Roth conversions.
THE 529
A college savings account behaves like a Roth (no federal deduction going in, but no tax on profits going out). Great gift from Grandma, since the money is out of her estate but she can still get it back if she needs it for a nursing home.
Reform target? Probably not, even though the prime winners here drive BMWs.
What to do: If there’s any chance the student will qualify for “financial assistance,” beware of the confiscatory taxes imposed on 529s by college bursars. You can avoid those taxes by playing a well-timed shuffle with the beneficiary designation and then disbursing the money in the kid’s senior year.
HEALTH SAVINGS ACCOUNTS
HSAs, to which contributions can be made on behalf of workers in a high-deductible insurance plan, are even better than most retirement savings. The only triple-tax-free investment out there has you (or your employer) deducting money going in, letting it compound tax-free, then getting it out tax-free to cover out-of-pocket costs incurred anytime after you got into the high-deductible plan. Permitted costs include Medicare premiums but not premiums for private insurance.
Risk of congressional attack? Low.
What to do: Avoid using the account for the intended purpose, which is to cover medical costs as they are incurred. Instead, let the money compound undisturbed for 40 years. Save all those co-pay receipts in a shoebox. For a couple, the correct strategy is for the survivor to cash in both accounts immediately after one of them dies. That’s because a surviving spouse can combine the accounts and match them to the shoebox, while any other heir would have to pay income tax on the money.
MORE FROM FORBES