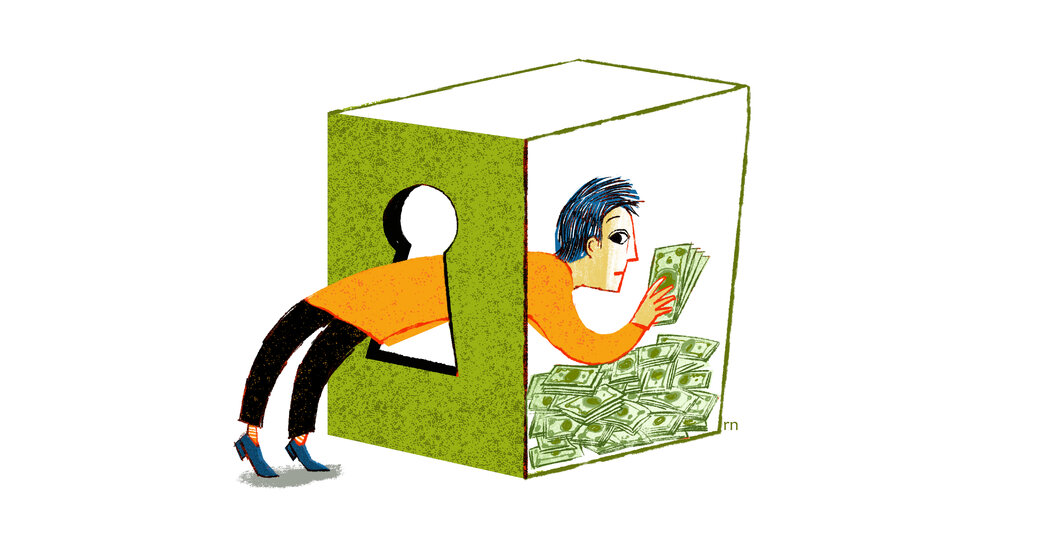
Sometimes, it’s illegal to spend money that you set aside for yourself.
When you save money in many types of workplace retirement accounts, the Internal Revenue Service doesn’t collect income taxes on that money until it’s time to take it out, when you’re older.
Need money before then? Certain types of “hardship” withdrawals are permissible. But you must have a very good reason, and you definitely can’t lie about it.
Last week, a sentencing hearing took place after a rare case involving this sort of legal violation. Federal prosecutors had won convictions against Marilyn Mosby, the former Baltimore prosecutor who may be best known for pursuing charges against the police officers in connection with the death of Freddie Gray in 2015, for both impermissible withdrawals and making a false mortgage application when she bought a condo in Florida.
Ms. Mosby will spend up to 12 months in home confinement, absent a successful appeal or a presidential pardon, which she has requested.
Her case is a complicated one, given that the sentence isn’t just for impermissible withdrawals. And her false claim of financial hardship to withdraw money from her city retirement account took place during the coronavirus pandemic in 2020, when alternative, one-time-only rules were in effect.
Still, hardship withdrawals are widely available.
What follows are some questions and answers about what happened in Ms. Mosby’s case and what the rules actually are. Keep in mind that employers have a fair bit of discretion in how they set up the rules for their retirement plans, and there may be slight differences between the rules for 401(k)s, 403(b)s and 457 plans.
Just to get this straight: Can you really go to jail for taking money out of your own workplace retirement savings account?
Yes. Although the judge allowed Ms. Mosby to avoid prison, prosecutors tried to put her there.
But this was her own money, right?
Technically, the money belongs to the trust that contains the retirement plan, but there are plenty of restrictions on what it can do with money that it holds for participants.
“It’s the plan’s money that you have certain rights in,” said Kelsey Mayo, a lawyer and benefits expert based in Charlotte, N.C. “You may have a right to the money, but you may not have a right to the money right now.”
OK, but why do any of these restrictions exist at all?
It’s a privilege to wait decades before paying income taxes the way you can with workplace retirement accounts. In exchange, lawmakers want to make sure that people use the money for their own old age and not for other things.
“If you want access at any time, don’t take the tax break,” Ms. Mayo said.
So how do these ‘hardship’ exceptions work?
Lawmakers understood that stuff happens, but they only wanted to let people (who are not yet of retirement age) pull money from retirement savings if it was really bad stuff.

So if your employer allows it, you can make a withdrawal if you are experiencing hardship. What does “hardship” mean? Start with whatever definition your employer provides, if any.
In its F.A.Q. on these hardship distributions, the I.R.S. says that withdrawals from 401(k) plans must be made because of “an immediate and heavy” need and the amount must be appropriate given the size of the need. You’re also supposed to have exhausted “other resources” before turning to a hardship withdrawal.
The I.R.S.’s examples of qualifying needs that an employer could allow include medical expenses, education-related bills, the threat of eviction or foreclosure and funeral costs.
You’ll generally pay taxes on hardship withdrawals, and you can’t pay the money back to your retirement plan the way you can when you take out a 401(k) or similar loan.
Are the early withdrawal rules different for individual retirement accounts?
Yes, they are more lenient but there are still taxes in many instances.
The hardship rules for workplace retirement plans changed in 2020, just for that year. What was different?
The primary change was a looser definition of hardship. People could withdraw up to $100,000 if they, as a memo from Ms. Mosby’s retirement plan administrator put it, experienced “adverse financial consequences as a result of being quarantined, furloughed, laid off, suffering reduced work hours or are unable to work due to lack of child care.”
What hardship did Ms. Mosby claim and how did prosecutors convince a jury that it wasn’t true?
Ms. Mosby kept her day job during the pandemic, but she also started a couple of side businesses — before the coronavirus outbreaks began — that she said were affected in 2020.
The jury didn’t believe her hardship was real, even though the administrator of her 457 plan, Nationwide, had allowed her withdrawal. (She bought two properties in Florida within months of the withdrawals.)
Did federal prosecutors charge lots of people with committing similar crimes in 2020?
No. I could not find any others, and the U.S. attorney’s office in Maryland declined to comment on the existence of other cases. If anyone knows of any, please send them my way.
Have people been in legal trouble for hardship withdrawal fraud in general?
There seems to be only a handful of cases in the last 20 years. Some involve individuals who lied about their circumstances and plans for the money. Others involve people who helped their colleagues make improper hardship withdrawals.
How much do I have to worry about getting in trouble for making an impermissible hardship withdrawal?
If you tell the truth, you have nothing to worry about. But a recent change in federal law could make it easier for more people to stretch the truth.
One result of the Secure 2.0 Act of 2022 is that it may become more likely for employers to let employees self-certify their hardship. If an employer allows it, workers can attest to the facts of their situation without needing to give financial documents to an employer to back it up.
Without employers keeping workers in check, people may be more tempted to fib. If they do, it’s up to the I.R.S. to sniff it out in any audit, in which case you would almost certainly need documents to prove hardship.
What alternatives should people consider before making a hardship withdrawal?
If you’re in a tough spot, you may well have thought of most possibilities already. But you may want to consider a loan from your workplace retirement plan, if it offers that option. Just keep in mind that repeated borrowing could compromise your savings and force you to work longer or retire with much less money.
Susan Beachy contributed research.